
Where the line actually falls
Almost everything about commercial financing turns on one boundary, and many investors get it wrong.
| Property | Treated as | Why it matters |
|---|---|---|
| One to four units | Residential | Single family through fourplex. Priced lowest, widest choice of lenders, and what most private money programs are built for. |
| Five or more apartments | Multifamily, commercial | Financed as commercial multifamily. Different lenders, different underwriting, usually higher rates. |
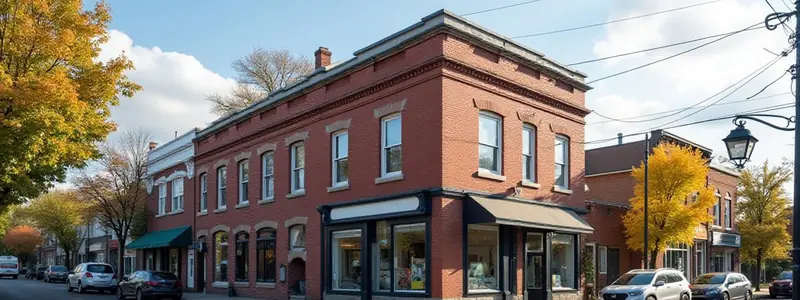
| Any commercial component | Often commercial | A shop downstairs and three apartments above is mixed use, and many lenders finance it as commercial even though it has fewer than five units. |
The property types investors bring
Commercial covers a wide range of income-producing property, and each type is underwritten differently.
Because short-term commercial underwriting leans on the property more than on tax returns, it can suit self-employed investors and small business owners who document poorly on paper but hold real property. It is still credit: the lender reviews you, the property and the plan, and decides.
Have a commercial property in view?
Send the address, the asset type, the rent roll and your plan. Our lending partner's team reviews whether it fits and on what terms. The lender makes every credit decision.
What commercial hard money costs
Commercial hard money generally costs more than residential, because the properties take longer to lease up or sell and income-producing property is more complex to underwrite. In 2026, short-term bridge financing across property types has commonly been quoted around 8% to 14% interest plus points, and the spread inside that range follows the property.
| Asset | Pricing tendency | Why |
|---|---|---|
| One to four unit residential | Lowest | Deep resale market, easiest to value. |
| Apartments and industrial | Tighter | Steady demand and many comparable sales. |
| Office, retail, hotel, special use | Wider | Value rides on leases and tenants rather than on the building. |
| Land and ground-up | Highest | Completion risk sits on top of everything else. |
Speed is still the reason to use it. Private money can usually close well ahead of a bank, and on a competitive commercial acquisition that difference can decide who gets the property. The lender decides when a file is ready to close.
What moves commercial pricing that does not apply residentially
- Asset class. Multifamily and industrial tend to price tighter. Hotels, office and special-use property price wider.
- Tenant credit quality. On a leased property, the strength of who is paying the rent is part of the underwriting.
- Recourse or not. Non-recourse generally prices higher than full recourse, all else equal: you are paying for the lender's reduced remedy.
- Market tier. Primary markets price tighter than secondary, and secondary tighter than tertiary.
- Prepayment structure. On longer-term commercial debt, yield maintenance and defeasance allow tighter pricing than a step-down or open prepayment.
The classic commercial value-add
Worth understanding even if you never do one, because it is the shape many commercial bridge deals take.
An investor buys an underperforming apartment building: say fifty units at sixty-five percent occupancy. A bank may not lend on it in that condition. Short-term private money finances the acquisition and the renovation. The investor refurbishes units and common areas, raises rents to market, and pushes occupancy up. Once it is stabilized and performing, it refinances into longer-term bank or agency debt at a lower rate.
The short-term money made the whole thing possible, and it was only ever meant to be held for a year or two. That is the pattern: expensive money buying the time to make a property bankable.
Office and retail are harder than they look. Their value depends on lease structures and tenant quality rather than on the building, so a lender who mostly finances residential flips may misjudge one. If that is your property type, find a lender who regularly finances it.
Mixed use: the useful middle ground
This is the part worth knowing, because it is under-served.
Some lenders write long-term DSCR-style loans on small mixed-use buildings when the building is mostly residential: apartments above, a shop or an office below. They qualify the loan on the rent from both the commercial and residential tenants rather than on your personal income.
If you have found a building with stable commercial tenants and a residential majority, that is a genuine niche with less competition than pure residential. See how DSCR loans are sized for the residential side of the math.
A word on regulation
Loans made primarily for business or commercial purposes are exempt from the federal Truth in Lending Act's consumer rules under Regulation Z. State oversight varies: some states require private lenders and loan arrangers to hold a license, others have little supervision of business-purpose lending.
Practically, that means the burden of checking sits with you. Check licensing where the property is, ask for references from past deals in that property type, and read the commitment before signing it. A lender who handles residential flips well may have no business underwriting a two-hundred-unit repositioning, and the wrong choice costs weeks, non-refundable deposits, and sometimes the deal. Our guide to choosing a lender lists the questions to ask.
Get your deal reviewed
Answer these and your deal goes to our lending partner's team, who will contact you about whether it is fundable and on what terms. By sending it you agree to your details being shared with them. Investment property only: our lending partners do not finance a home you will live in.
Got it.
Thank you. Your details are on their way to our lending partner's team, who will contact you shortly.
Commercial financing questions
Can I get a hard money loan on a commercial property?
Yes. Short-term private lenders finance apartment buildings, mixed use, self-storage, office, retail and industrial property. Our lending partners review commercial deals on a case-by-case basis; send the asset type, size and location, and confirm loan size, leverage and term with the lender for your property.
What makes a property commercial rather than residential for financing?
Five or more apartment units, or a commercial component such as a shop or office. A storefront with three apartments above is mixed use, and many lenders finance it as commercial even though it has fewer than five units.
What interest rate should I expect on commercial hard money?
In 2026, short-term commercial bridge money has commonly been quoted around 8% to 14% plus points. Apartments and industrial sit toward the tighter end; office, retail, hotels and land sit toward the wider end. The lender prices each deal.
Can I use a DSCR loan on a mixed-use building?
Sometimes. Some lenders write DSCR-style loans on mixed-use buildings that are mostly residential, qualifying on the rent from both kinds of tenant. Expect lower leverage and a higher required coverage ratio than on a pure residential rental.
Are business-purpose hard money loans regulated?
Business-purpose loans are exempt from the federal Truth in Lending Act's consumer rules, and state oversight varies widely. Some states require lenders to hold a license; others barely supervise business-purpose lending. Check licensing where the property sits.
Why does a non-recourse commercial loan cost more?
Because the lender's remedy is limited to the property. All else equal, non-recourse prices above full recourse: you are paying for what the lender gives up.
Sources
- CFPB, Regulation Z, 12 CFR 1026.3 Exempt transactions, business-purpose credit exemption (accessed Oct 2026)
- RentalRealEstate.com, bridge loans (updated April 2026), 2026 bridge rate ranges (accessed Oct 2026)
Dominion Hard Money does not lend its own funds; it arranges financing through third-party lending partners. All financing is arranged for business purposes only and secured by non-owner-occupied investment property. Not a commitment to lend. All loans subject to underwriting, property review, and approval by the lender. Terms vary by property, borrower experience, and exit strategy.